Snitch Revenue Grows 68% To Rs 835 Cr In FY26, Posts Rs 27 Cr Loss
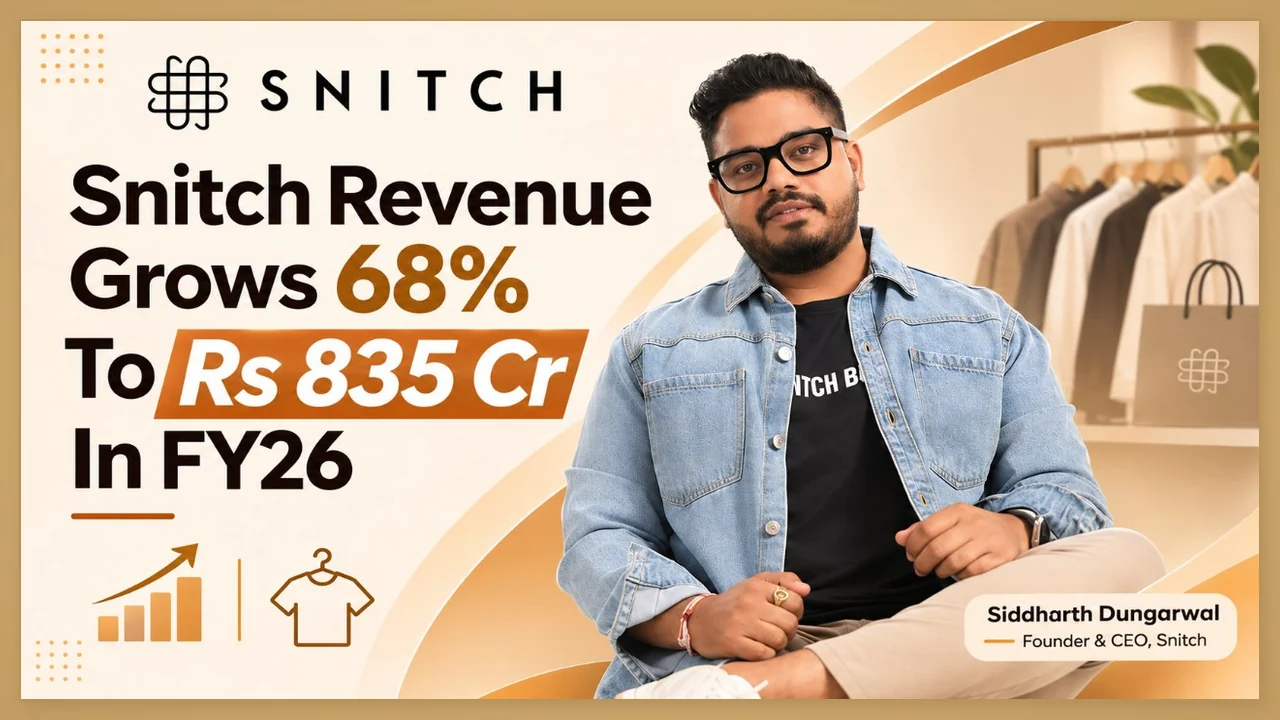
Snitch, the men’s fast-fashion brand, grew revenue from operations by 67.7% to Rs 835 crore in FY26 from Rs 498 crore in FY25, according to its annual financial statements filed with the Registrar of Companies.
Total income reached Rs 849 crore, including Rs 14 crore of other income from interest on deposits and long-term investments. The company posted a net loss of Rs 27 crore for the year.
The FY26 Numbers
Snitch spent Rs 1.05 to earn a rupee of revenue in FY26. Its total expenditure rose 71.9% to Rs 873 crore. Is slightly faster than revenue growth and explains the loss.
Read More: Sachin Tendulkar Invests In Metasports, Hitwicket Targets 100 Mn Downloads
Snitch reported an EBITDA margin of -3% and a return on capital employed of -8.6%. Both numbers say the same thing: the business is still buying scale.
Read More: Ayesha Gupta’s AYURZAA Focuses on Awareness and Everyday Women’s Wellness
Snitch has grown revenue 3.4 times over the past two fiscal years while holding losses relatively contained. That combination is rarer in Indian D2C fashion than the growth itself.
Where the Money Went
Procurement of apparel and accessories was the largest cost, at about 51% of total expenditure. It rose 92.2% to Rs 444 crore from Rs 231 crore a year earlier.
Advertising and marketing cost Rs 108 crore, employee benefits Rs 81 crore, with marketplace charges, rent and delivery on top. The ad number is the one to watch, because fashion brands that buy growth usually cut marketing last.
Inventory is the hidden risk in that cost line. A fast-fashion label that expands assortment quickly ends up holding stock it cannot sell at full price. Markdowns destroy the margin it was chasing.
The Offline and Quick Commerce Bet
Snitch operates 142 stores across India, including metro and Tier II cities, according to its website. It has also entered quick commerce to widen reach and speed up delivery.
Stores solve two problems at once. They generate revenue without customer acquisition cost. They act as dark stores for returns and exchanges, which is where online fashion loses margin.
Quick commerce is the more speculative move. Apparel is not a grocery category. A ten-minute promise only works for basic items where size risk is low.
Losses Under Control
For Snitch, a Rs 27 crore loss on Rs 835 crore of revenue works out to roughly 3% of sales. For a fashion brand growing at 68%, that is a disciplined number.
Most D2C apparel companies in India run losses in double digits as a share of revenue while scaling. Snitch is close to breakeven at the EBITDA level. Suggests the business could turn profitable by slowing expansion rather than by raising prices.
The company has raised over $53 million to date, including a $40 million Series B led by 360 ONE Asset in June 2025. That capital base is what allows a 3% loss to be a choice rather than a crisis.
What to Watch
Three things will decide whether FY27 is the year Snitch turns profitable. The first is gross margin, because procurement growing faster than revenue at 92% is a warning sign on discounting.
The second is same-store sales. With 142 stores, growth from new outlets flatters the number. The metric that matters is whether older stores are selling more than last year.
The third is the quick commerce experiment. If apparel on ten-minute delivery works, it becomes a genuine moat. If it does not, it is a marketing cost with a logistics bill attached.
Sudip Kumar is a Writer at Bharat Fast, contributing to the platform for more than six months. With an interest in startups, entrepreneurship, digital media and graphics designing, he enjoys exploring emerging businesses and sharing informative stories with readers.
More from this section
InMobi Secures Ibbaluru Metro Station Naming Rights For Rs 65 Cr
Sarvam Appoints Google Cloud India MD Sashikumar Sreedharan As President, CBO
DriveU Net Profit Doubles To Rs 3.6 Cr In FY26 As NTV Hits Rs 131 Cr