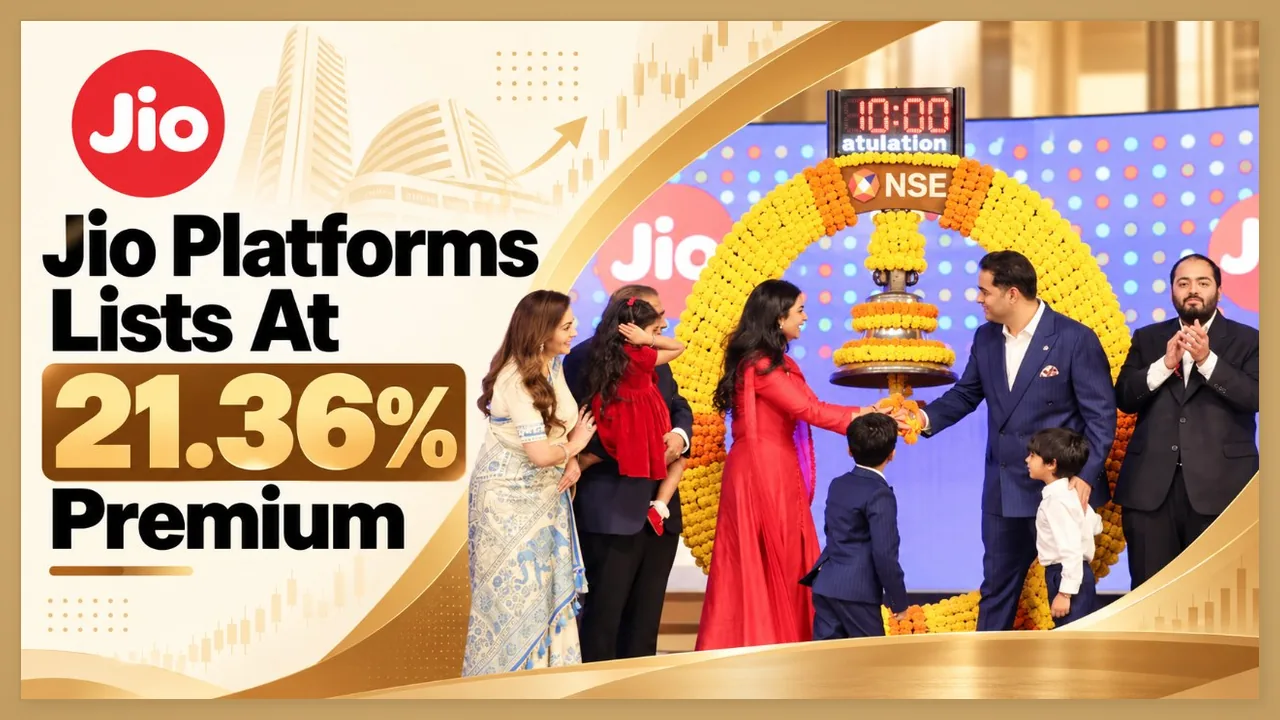
Jio Platforms listed on the exchanges at Rs 1,358, a 21.36% premium to its issue price of Rs 1,119, despite a weak broader market. By 3:01 pm on listing day the stock traded at Rs 1,414, up 26.4% from the issue price.
The Rs 30,213 crore IPO was India’s largest, and the listing gives Reliance Industries a public currency for its digital business five years after the unit was incorporated in November 2019.
Read More: Kissht Parent OnEMI Gets BSE, NSE Nod For Rs 832 Crore Share Issue
Read More: Indian Startup Funding This Week: 15 Startups Raise $133.9 Mn, Down 56%
The Listing Day Numbers
At Rs 1,414, Jio Platforms carries a market capitalisation of about Rs 10,73,289 crore. Reliance Industries holds 66.43% of the company. At that price, its stake is worth roughly Rs 7.1 lakh crore.
The stock trades on the BSE under the code 545004 and on the NSE as JPL. The face value is Rs 10.
The debut matters because the offer was large enough to absorb serious selling pressure, and Jio Platforms still opened 21% higher. A 21% opening pop on a Rs 30,000 crore issue, in a market that was otherwise weak, tells you how much institutional money was waiting for this paper.
What the Valuation Says
At the current price the stock trades at a price-to-earnings ratio of about 35.6. Return on capital employed stands at 12.1% and return on equity at 9.41%.
Those are not software multiples. They are the numbers of a capital-intensive connectivity business with a large asset base. That is exactly what Jio Platforms is: the parent entity of Reliance Jio Infocomm, with networks, devices, applications and content inside one structure.
The gap between the 35.6 P/E and the 9.41% ROE is the question investors will spend the next year arguing about. Either earnings grow fast enough to justify the multiple, or the stock de-rates towards what the balance sheet supports.
Why the IPO Was This Large
Rs 30,213 crore makes it the biggest Indian share sale ever. It also lands in a primary market that has been absorbing size without trouble. The National Stock Exchange listing and this one have both shown the same thing. Domestic institutions and retail together can fund deals of this scale.
For Reliance, the listing does three things. It creates a market price for the digital business, it gives the group a route to monetise without borrowing, and it opens the door to index inclusion, which brings passive money automatically.
That last point is the mechanical part of the trade. Once Jio Platforms enters the benchmarks, every index fund tracking them has to buy, regardless of what the analysts think about the P/E.
The Risks the Prospectus Carries
The first is competition. Bharti Airtel and Vodafone Idea operate in the same market. Tariff decisions by any one of them reset the economics for all three. Jio has led price moves before, and it can lead them downwards as easily as upwards.
The second is capital intensity. Spectrum, 5G rollout and network upgrades consume cash every year, and the 12.1% ROCE reflects that. A business that reinvests heavily can compound for a long time. It does not throw off free cash the way asset-light models do.
The third is the holding company structure. Investors are buying Jio Platforms, not Reliance Jio Infocomm directly. The value of any holding company depends on how Jio Platforms and Reliance allocate capital across digital, AI, education and media assets.
What to Watch
Three things will decide whether the listing pop holds. The first is the first quarterly result as a listed company, because that is when guidance becomes a public commitment rather than a private plan.
The second is index inclusion for Jio Platforms and the flows that follow it. The third is the lock-in expiry for anchor and pre-IPO shareholders, which is when supply arrives and the stock has to stand on earnings rather than scarcity.
For now, the market has priced Jio Platforms as India’s digital infrastructure company with a growth premium attached. Whether that premium survives its first year of quarterly reporting is the only question that matters.